For a short time only! $1.99.
You get the full package.
Friday, July 19, 2013

Thursday, July 4, 2013
Introduction to downloading financial data added
A short introduction to downloading financial data has been posted. It's available at http://quantlua.com/WP/2013/07/05/downloading-financial-data/
Saturday, June 22, 2013
Six Reasons to get QuantLua
QuantLua is a new app available on the app store. It is made especially for people in quantitative finance, or learning finance and financial engineering, but useful for others too. It consists of two main parts: the QuantLib/Lua programming environment and the historical stock simulator. These two components can be used separately, but have been built to work together well. With QuantLua you are able to download historical data, analyze it and display it in various ways.
Here are 6 good reasons why you want to get QuantLua.
1. The graphics are impressive. What other app allows you construct your own plots to analyze various aspects of the stock market? You are not constrained by the graphs provided, you can take the examples provided and make them suit you.
2. There are many functions at your disposal, and many more to come. QuantLua is built on two well tested pillars, Lua and QuantLib. Lua is a full fledged programming language with features not found in other languages. QuantLib is a powerful computational finance library providing with lots of functionality. If you do not find the function you need, you can create it yourself or ask.
3. It is fun and educational. The stock simulator can be used to teach about how the stock market works. It can be used as game to test how good a trader you are (or were) compared to your friends.
4. It is cheap. There is no other program on any platform with as much functionality as QuantLua at such a low low price. Only custom built platforms costing tons of money can provide such functionality.
5. You are in control. We have provided examples of what you can do, but ultimately you are not hemmed in by our examples. You can try your own ideas, including things we have never imagined.
6. There is support. QuantLib has a very strong online community where you can learn more on how to use it. Lua has been around for a very long time and has gathered a huge following due to its versatility. As always, we are always here to help.
So don't hesitate: head over to the iTunes App store and grab yourself a copy
Here are 6 good reasons why you want to get QuantLua.
1. The graphics are impressive. What other app allows you construct your own plots to analyze various aspects of the stock market? You are not constrained by the graphs provided, you can take the examples provided and make them suit you.
2. There are many functions at your disposal, and many more to come. QuantLua is built on two well tested pillars, Lua and QuantLib. Lua is a full fledged programming language with features not found in other languages. QuantLib is a powerful computational finance library providing with lots of functionality. If you do not find the function you need, you can create it yourself or ask.
3. It is fun and educational. The stock simulator can be used to teach about how the stock market works. It can be used as game to test how good a trader you are (or were) compared to your friends.
4. It is cheap. There is no other program on any platform with as much functionality as QuantLua at such a low low price. Only custom built platforms costing tons of money can provide such functionality.
5. You are in control. We have provided examples of what you can do, but ultimately you are not hemmed in by our examples. You can try your own ideas, including things we have never imagined.
6. There is support. QuantLib has a very strong online community where you can learn more on how to use it. Lua has been around for a very long time and has gathered a huge following due to its versatility. As always, we are always here to help.
So don't hesitate: head over to the iTunes App store and grab yourself a copy
Introduction to the plot command.
An introduction to the plot command is now up at the quantlua support site
This is one of the most important commands as it enables you to create a wide range of plots.
This is one of the most important commands as it enables you to create a wide range of plots.
Thursday, June 20, 2013
Discount for a limited time.
QuantLua will be selling at 40% discount from now until the end of the month.
Hurry while offer lasts!
Hurry while offer lasts!
Friday, June 14, 2013
QuantLua now approved for the iTunes App store.
QuantLua has been approved for the app store and is scheduled to appear shortly.
The app is available here
QuantLua is the most comprehensive financial application available for the iPhone. It has these main features:
-A programmable historical stock simulator for select US stocks
-The most comprehensive finance calculator available, incorporating the QuantLib quantitative finance library and the programming language Lua.
-Excellent graphics library for building your own plots. It includes line graphs, bar graphs and pie charts.
The historical stock market simulator is for select US stocks. It enables you to build a portfolio and see how the strategy would have performed over time. It is also fully programmable, enabling the analysis of dynamic strategies.
Also included is a historical stock and currency data feed. This imports stock data from Yahoo Finance and currency data from OANDA directly into the Lua programming engine.
All this is powered by Lua, an intuitive and complete programming language well suited to financial analysis.
The app is available here
QuantLua is the most comprehensive financial application available for the iPhone. It has these main features:
-A programmable historical stock simulator for select US stocks
-The most comprehensive finance calculator available, incorporating the QuantLib quantitative finance library and the programming language Lua.
-Excellent graphics library for building your own plots. It includes line graphs, bar graphs and pie charts.
The historical stock market simulator is for select US stocks. It enables you to build a portfolio and see how the strategy would have performed over time. It is also fully programmable, enabling the analysis of dynamic strategies.
Also included is a historical stock and currency data feed. This imports stock data from Yahoo Finance and currency data from OANDA directly into the Lua programming engine.
All this is powered by Lua, an intuitive and complete programming language well suited to financial analysis.
Tuesday, June 11, 2013
Small fix for an example script
The script "UserScripts/Graphics/Function" has a small bug. It should be
-- define function
local function fc(x)
return math.cos(x)
end
local function fs(x)
return math.sin(x)
end
plot({f=fs,x={0.5,4},p=20,r=1,w=1,c=2},
{f=fc,x={1,5},c=1,r=1,w=1})
Friday, June 7, 2013
Thursday, April 11, 2013
Call for testers!
I am in the process of testing the application QuantLua in preparation for release in the next few weeks. If you would like to test it then please contact me on tgwena(a)gmail.com and we can make arrangements.
Hurry! Space is limited (by Apple)
Hurry! Space is limited (by Apple)
Monday, April 8, 2013
Life on the big(ger) screen (iPhone 5)
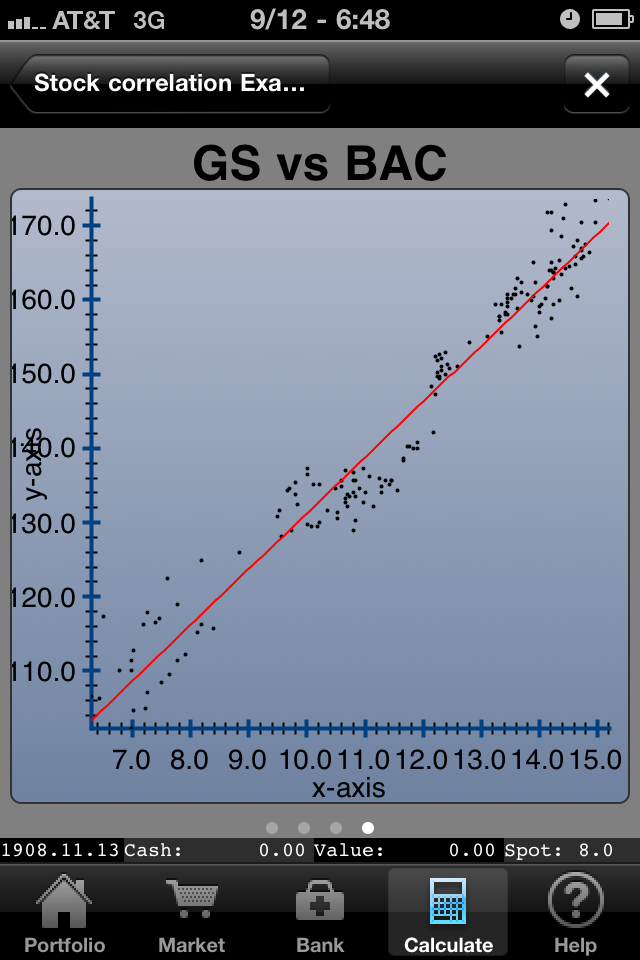
The iPhone 5 display provides more space for bigger, better graphs. Look at the examples below:


Sunday, March 24, 2013
iPhone 5 and instruction manual
Just completed porting to iPhone 5. Running on a dual core machine presented interesting challenges.
Also put up a draft of the instruction manual.
Also put up a draft of the instruction manual.
Sunday, February 3, 2013
Feature list.
This is a comprehensive summary of the features found in Financial Game (provisional name, subject to change)
1. A programmable simulation engine using historical stock prices

2. A comprehensive calculator with the following
a. Programmable in Lua, a stable mature language well suited to financial calculations.

b. Full access to the QuantLib financial library


c. Extensive graphics capabilities, including line graphs, pie charts, bar graphs.

d. Access to historical stock and currency data


1. A programmable simulation engine using historical stock prices

2. A comprehensive calculator with the following
a. Programmable in Lua, a stable mature language well suited to financial calculations.

b. Full access to the QuantLib financial library


c. Extensive graphics capabilities, including line graphs, pie charts, bar graphs.

d. Access to historical stock and currency data


Thursday, January 31, 2013
Running two historical simulations
Running two simulations of IBM starting from 1981 going through the 1987 crash.
The code for the first simulation:
The second simulation does the opposite (this is the red line):
The results of the simulation are in the graph below:

A note on the code.
A stock object is created simply by saying 'stock(symbolstring)' e.g. 'stock("ibm")'. Adding or subtracting assets to a portfolio is done by a regular +, so the line
_=P+10*s
simply adds ten shares of s to the portfolio P.
Dividing a portfolio by a stock give a count of how many shares are in that portfolio.
P/s is the count of the number of share in P.
The code for the first simulation:
local s=stock("ibm")
local p=currpf()
if s:price(-1)>s:price() and p/s<10 then
_=p+10*s
end


if s:price(-1) <s:price() and p/s>0 then
_=p-10*s
end
This code is run daily and does the following: Buy 10 IBM stock if yesterday's price is higher than today, otherwise sell if yesterday's price is lower. This is essentially bucking the trend. This is the blue line.
The second simulation does the opposite (this is the red line):
local s=stock("ibm")
local P=currpf()
if s:price()>s:price(-1) and P/s<10 then
_=P+10*s
end
if s:price()<s:price(-1) and P/s>0 then
_=P-10*s
end
The results of the simulation are in the graph below:

A note on the code.
A stock object is created simply by saying 'stock(symbolstring)' e.g. 'stock("ibm")'. Adding or subtracting assets to a portfolio is done by a regular +, so the line
_=P+10*s
simply adds ten shares of s to the portfolio P.
Dividing a portfolio by a stock give a count of how many shares are in that portfolio.
P/s is the count of the number of share in P.

Sunday, January 27, 2013
Saturday, October 8, 2011



Sunday, January 23, 2011
Reading Yahoo/Fed data directly
I can now use Lua to read in Federal-H15 data and Yahoo stock data. directly into QuantLib/Lua. I just wish I could read bond data from somewhere :-(
Friday, January 7, 2011
Thursday, January 6, 2011
Pricing a bond using QuantLib/Lua
Here is an example of pricing a bond using QuantLib/Lua on the iPhone
--Simple bond pricing
--http://tgwena.blogspot.com
ql=QuantLib
Date=ql.Date
local sDD=Date(17,5,1998)
local eDD=Date(17,5,2001)
local r=0.04 --interest rate
local c=0.06 --coupon
ql.Settings_instance():setEvaluationDate(sDD)
sched=ql.Schedule(sDD,eDD,ql.Period(2),ql.NullCalendar(),ql.Unadjusted,ql.Unadjusted,0,false)
ufixQ=ql.SimpleQuote(r)
ufixH=ql.QuoteHandle(ufixQ)
curve=ql.FlatForward(0,ql.NullCalendar(),ufixH,ql.SimpleDayCounter())
flatTS=ql.YieldTermStructureHandle(curve)
bondEngine=ql.DiscountingBondEngine(flatTS)
bond=ql.FixedRateBond(0,100,sched,ql.DoubleVector(1,c),ql.SimpleDayCounter(),ql.Unadjusted, 100, sDD)
bond:setPricingEngine(bondEngine)
print(bond:dirtyPrice())
Sunday, December 5, 2010
A sample Lua/QuantLib program
This example is a rip of the Python Lua example for European options:
It returns the values 0.030342732609191 and 0.030027071770314 respectively
-- Mostly ripped from Python European Example
-- makes life a little simpler
QL=QuantLib
Date=QL.Date
tD=Date(15,QuantLib.May,1998)
sD=Date(17,QuantLib.May,1998)
QL.Settings_instance():setEvaluationDate(tD)
print(QL.Settings_instance():getEvaluationDate())
riskFreeRate = QL.FlatForward(sD, 0.05, QL.Actual365Fixed())
exercise = QL.EuropeanExercise(Date(17,5,1999))
payoff = QL.PlainVanillaPayoff(QL.Option_Call, 8.0)
underlying = QL.SimpleQuote(7.0)
volatility = QL.BlackConstantVol(tD, QL.TARGET(), 0.10, QL.Actual365Fixed())
dividendYield = QL.FlatForward(sD, 0.05, QL.Actual365Fixed())
process = QL.BlackScholesMertonProcess(QL.QuoteHandle(underlying),QL.YieldTermStructureHandle(dividendYield),QL.YieldTermStructureHandle(riskFreeRate),QL.BlackVolTermStructureHandle(volatility))
option = QL.VanillaOption(payoff, exercise)
option:setPricingEngine(QL.AnalyticEuropeanEngine(process))
-- Analytic
print ("Analytic Price",option:NPV())
-- Finite Difference
-- method: finite differences
timeSteps = 801
gridPoints = 800
option:setPricingEngine(QL.FDEuropeanEngine(process,timeSteps,gridPoints))
print("finite diff.",option:NPV())
Subscribe to:
Posts (Atom)